Our team talks with family offices, principals and their advisors every day. One of the first questions we hear is whether a family has enough wealth to justify an office of its own, and most answers online stop at a single number. This guide shows what actually sets that minimum, so your family can pick the structure that fits before committing capital and staff to one.
We used AI tools to help gather research and speed up the first draft. That left more of our time for checking each figure against its original report and adding what we see in client conversations. A Masttro editor reviewed every claim, and members of our team read the article before it was published.
- J.P. Morgan Private Bank, 2026 Global Family Office Report
- UBS, Global Family Office Report 2025
- Deloitte Private, family office research (2024)
- Knight Frank, The Wealth Report 2026
- BMO Family Office, Form CRS (January 2026)
- U.S. SEC family office rule, 17 CFR 275.202(a)(11)(G)-1
- Duane Morris, Singapore 13O and 13U application criteria
Key Takeaways
Most advisors put the family office minimum net worth for a single-family office at $100 million in investable assets, and many prefer $250 million or more. The reason is cost: even offices managing $250 million or less spend about $0.9 million a year to operate, according to J.P. Morgan Private Bank's 2026 Global Family Office Report.
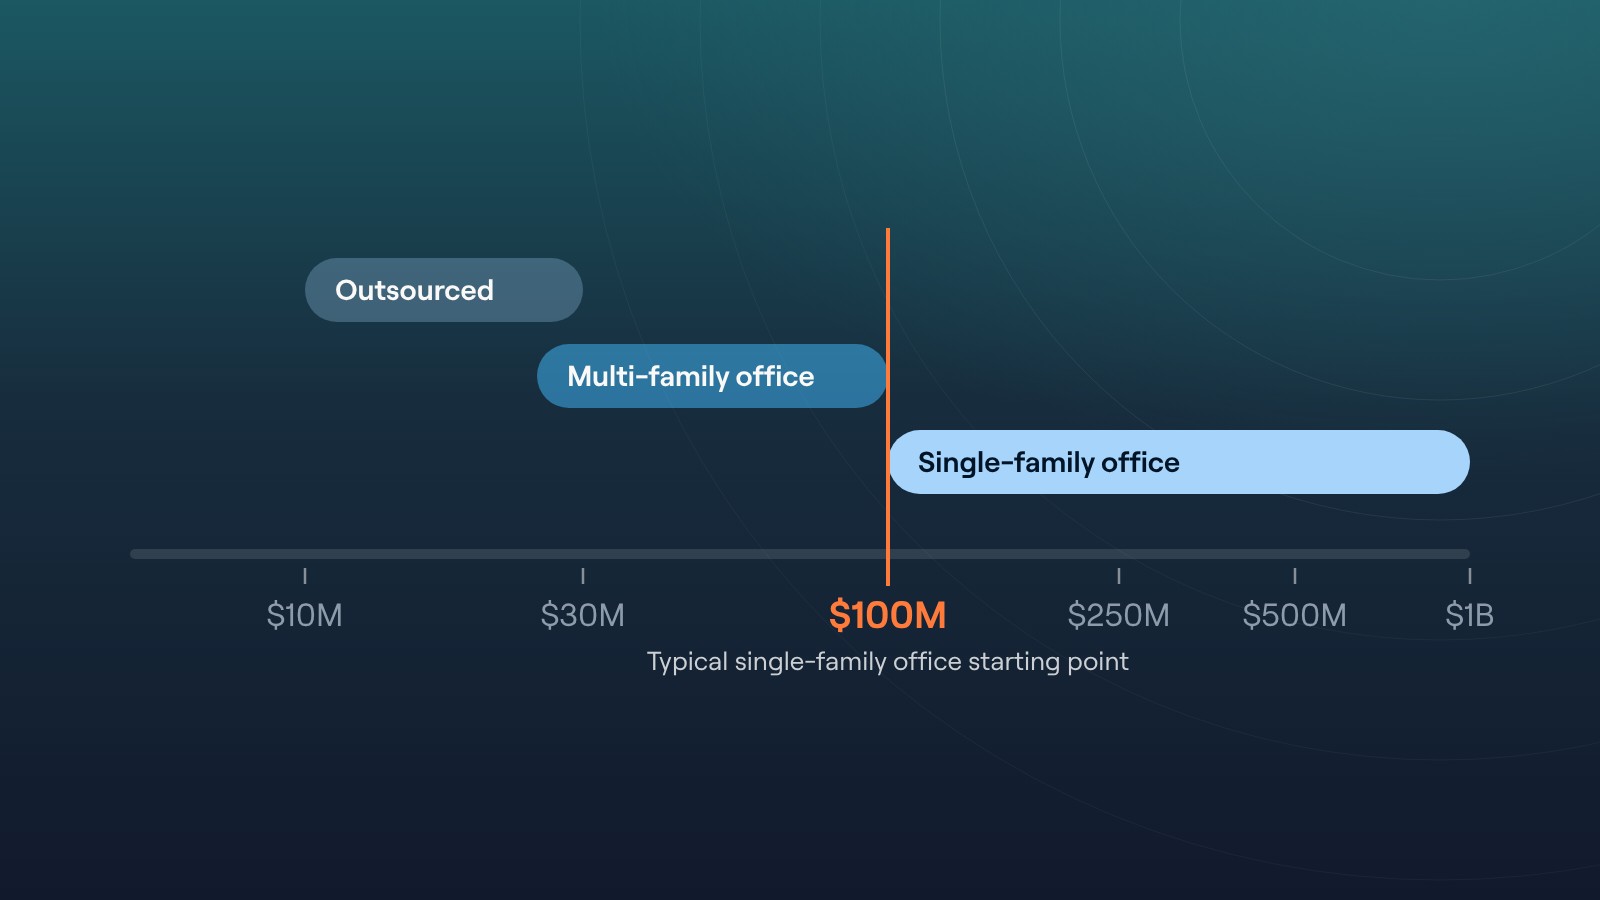
Below that level, ultra-high-net-worth families still have good options. A multi-family office shares the cost of a professional team across many families, and an outsourced family office coordinates private banking, tax and legal specialists on the family's behalf. This guide sets out the asset levels for each model, what each one costs, and the other factors that decide which structure fits.
What is the minimum net worth for a family office?
There is no legal minimum. A family office is a private company, and any family can form one. The practical minimum comes from the arithmetic: the office has to cost a small enough share of family wealth to be worth running. Here is where each model usually starts.
| Family office model | Typical starting point | What the family gets | Annual cost |
|---|---|---|---|
| Single-family office (SFO) | $100M+ in investable assets; $250M+ is comfortable | A dedicated team and full control over investments, estate planning and governance | About $0.9M at $250M or less, rising to $6.6M at $1B+ |
| Multi-family office (MFO) | $25M–$100M; some firms require $50M or more | A shared professional team with institutional services | Usually a percentage of assets or a fixed retainer |
| Outsourced or virtual family office | $10M–$30M | Specialists coordinated by a private bank, wealth manager or advisor | Fees paid to each provider |
These ranges are starting points, not rules. A family with $80 million spread across 30 entities in four countries may need a dedicated office sooner than a family with $300 million in a single brokerage account.
Why is $100 million the usual threshold for a single-family office?
A single-family office (SFO) is a private company that serves one family. It employs its own investment professionals and staff, often a chief investment officer, a CFO or controller, investment managers, tax and legal staff, and administrators. That team handles investment management, asset allocation, investment decisions, risk management, tax planning and tax preparation, estate planning, philanthropic planning and family governance for one set of family members, with no other clients competing for attention.
What does an SFO cost to run?
J.P. Morgan surveyed 333 SFOs in more than 30 countries for its 2026 report. Annual operating costs rise steadily with assets under management:
The average office spends about $3 million a year, and 40% spend under $1 million, according to J.P. Morgan's release of the report. Staff is the largest line. The UBS Global Family Office Report 2025 found that the average office employs 12 people.
What does that cost as a share of family wealth?
UBS puts the average pure operating cost at 41.1 basis points (0.41%) of assets a year. Dividing J.P. Morgan's average cost for each size band by the family's assets shows why $100 million is the floor most advisors use:
| Investable assets | J.P. Morgan's average cost for that size band | Cost as a share of assets |
|---|---|---|
| $50M | $0.9M (offices of $250M or less) | 1.8% |
| $100M | $0.9M (offices of $250M or less) | 0.9% |
| $200M | $0.9M (offices of $250M or less) | 0.45% |
| $500M | $1.7M ($250M–$500M) | 0.34% |
| $750M | $3.3M ($501M–$999M) | 0.44% |
At $50 million, a typical small office would consume nearly 2% of the family's assets every year before any investment fees, which is hard to justify against investment returns. At $100 million the figure falls under 1%, and by $200 million it sits close to the UBS average. That is why many advisors treat $100 million as the minimum and $250 million or more as the comfortable range.
Why do some advisors say $250 million or $500 million?
Advisors who set the bar higher are counting what a "full" office does. An SFO that runs its own investment teams, makes direct private equity and venture capital investments, and handles real estate management and operating companies needs more staff and more systems. A family with $100 million can run a lean office of two or three people that relies on outside investment managers for investment implementation. A family with $500 million can afford in-house research, risk analysis and a wider range of private investments.
How much do you need to join a multi-family office?
A multi-family office (MFO) serves several families with one shared team. Most MFOs look for families with $25 million to $100 million in investable assets, though minimums vary widely by firm. BMO Family Office, for example, states a $50 million minimum for discretionary accounts and $100 million for non-discretionary accounts in its Form CRS.
MFOs typically offer the same family office services an SFO would: investment strategies, estate planning and wealth transfer strategies, trusts and estates work, tax planning, philanthropic advisory for charitable giving and other philanthropic activities, and family governance. Each family pays for a share of the team instead of all of it. Fees are usually a percentage of assets or a fixed retainer. Ask any MFO how it is paid, whether it charges a performance-based fee or earns revenue from products it recommends, and how it manages conflicts of interest.
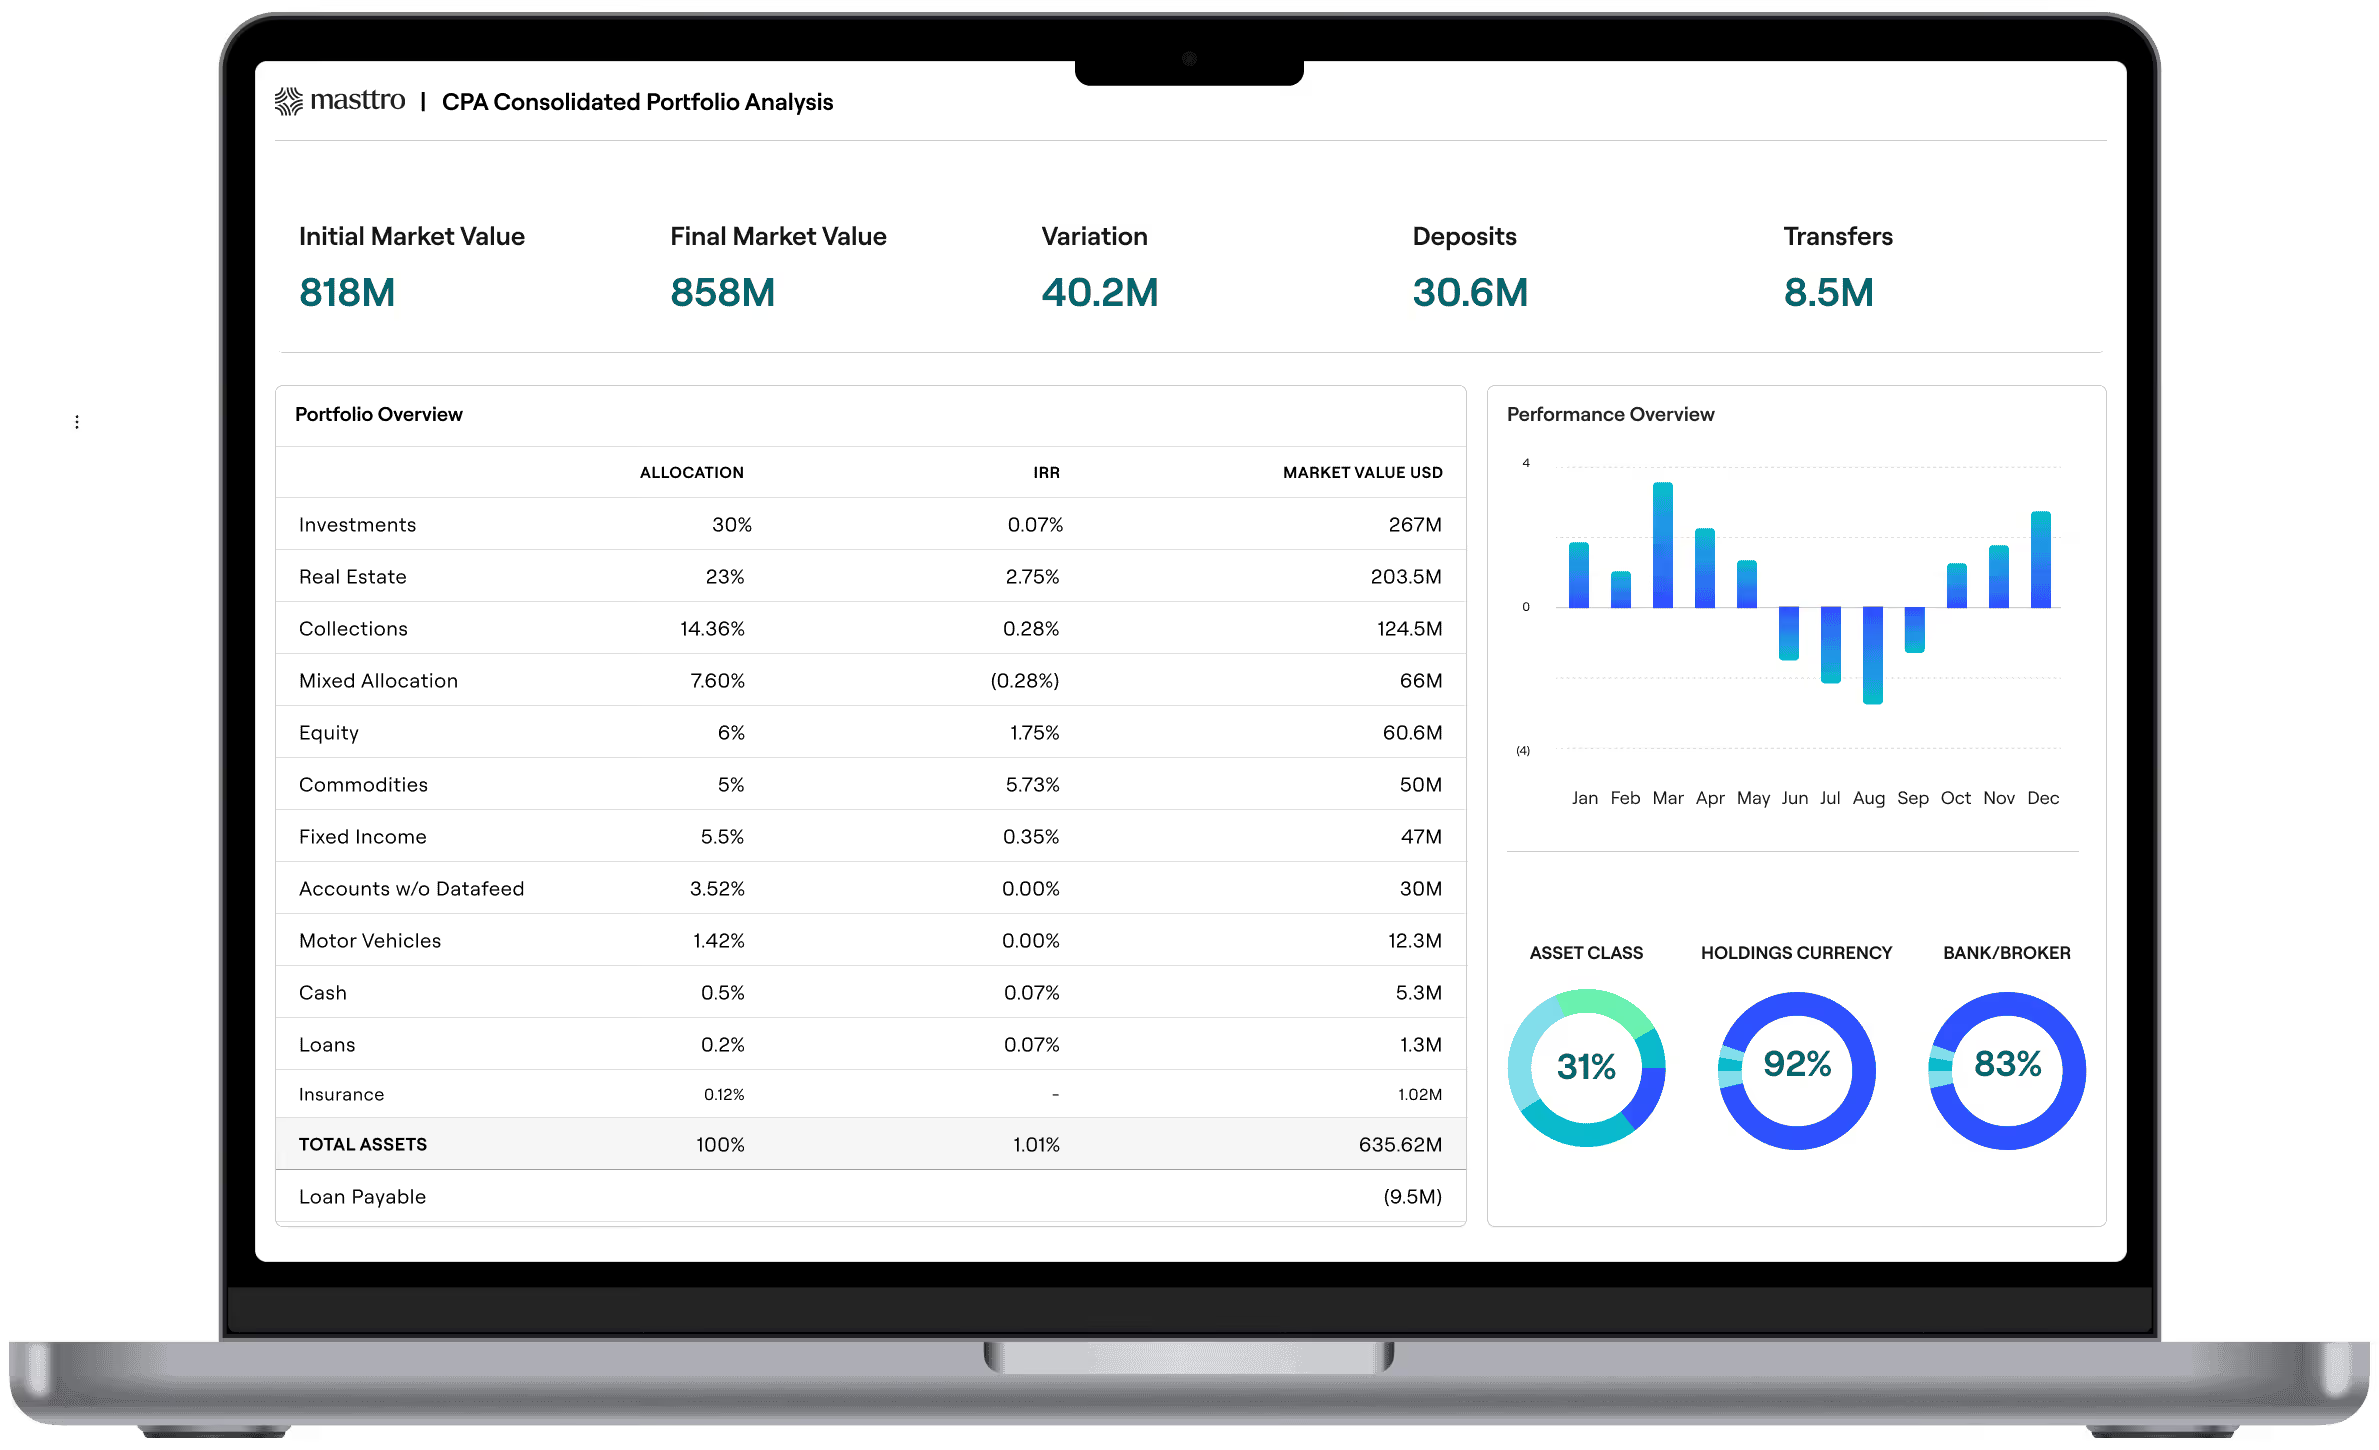
Many MFOs are registered investment advisers, which brings regulatory compliance obligations an SFO usually avoids. The main operating challenge for an MFO is scale: client service depends on consolidated reporting for dozens of ultra-high-net-worth families, often under the firm's own brand. Masttro's multi-family office software supports this with white-label client portals, portfolio analytics and client reporting across every household.
What are the options for families with $10 million to $30 million?
For families in this range, a dedicated office is too expensive and many MFOs will not take the account. The usual answer is an outsourced family office. In an outsourced family office, a private bank, wealth manager or independent financial advisor coordinates specialists in wealth planning, tax, estate planning, legal affairs and insurance. Most private banking groups and wealth management firms offer a version of this through their wealth management services. A virtual family office works the same way with the specialists connected remotely, and a fractional family office shares senior staff part-time.
Outsourcing is not only a small-family approach. Large SFOs outsource too:
J.P. Morgan found that about 52% of offices outsource legal work and more than 45% outsource trading, and only about one in five do everything in-house. The question for a smaller family is how much of the office to buy from outside providers, not whether to outsource at all. A family that starts with an outsourced family office can bring functions in-house one at a time as its assets grow.
Does net worth or investable assets decide the minimum?
Investable assets decide it. Net worth includes the family business, primary homes, art and other assets that do not produce income to pay an office's running costs. A founder worth $300 million on paper, with $280 million tied up in the family business, has about $20 million of investable assets. That puts the founder in outsourced or MFO territory until a liquidity event such as a sale or IPO.
When you assess readiness, count liquid investments, private fund commitments at their net asset value, and income-producing real estate. Then check whether the remaining assets add complexity that needs managing. A yacht, a collection or a stake in a family business does not pay for an office, but it does add reporting, insurance and asset protection work.
What other factors decide whether you need a family office?
Asset levels set what a family can afford. Complexity decides what it needs. Four factors push families toward a dedicated office earlier than the numbers alone suggest.
How many entities, countries and currencies are involved?
Family trusts, holding companies, private foundations and partnerships each need their own records, tax filings and reports. Add custodians in several countries and multiple currencies, and a family can outgrow private bank statements well below $100 million. Seeing the full ownership structure on a Global Wealth Map is often the first step.
How much of the portfolio is in private markets?
Private equity, hedge funds, venture capital and private credit generate capital calls, distributions, net asset value (NAV) statements and K-1s on their own schedules. J.P. Morgan's survey respondents held about 35% of their portfolios in alternatives on average. Each fund adds paperwork that someone has to track, reconcile and report, so a family with heavy exposure to private investments and hedge funds needs more operational capacity than a family with the same assets in listed securities. Read more in our guide to alternative investments for family offices.
Is a generational transition coming?
Family offices exist largely to manage wealth transfer and succession planning. When a second or third generation joins, family members need governance: a family council, investment policies, and clear rules on who sees which information. An office gives the family legacy a permanent home. Our family office strategy guide covers how families structure this.
How much privacy does the family need?
Some families build an office mainly to keep financial information within a small, trusted team. That depends on secure systems as much as on people. Our cybersecurity guide for family offices covers the main risks.
How many family offices are there?
Deloitte Private estimated there were about 8,030 SFOs worldwide in 2024, holding $3.1 trillion in assets, and expects 10,720 by 2030. The pool of potential founders is growing too: Knight Frank counted 713,626 ultra-high-net-worth individuals (net worth above $30 million) in 2026, up 162,191 in five years. Many of these high-net-worth families will reach the point where a private bank relationship no longer covers everything they own.
Do family offices have to register with regulators?
In the US, most SFOs rely on the SEC's family office exclusion to avoid registering as an investment adviser. To qualify, the office must have no clients other than family clients, be wholly owned by family clients and controlled by family members, and not hold itself out to the public as an investment adviser. Serving even one outside family usually ends the exclusion, which is why MFOs typically register.
Some jurisdictions tie family office tax incentives to a minimum fund size. In Singapore, funds applying for the Section 13O and 13U tax incentive schemes must hold at least S$20 million and S$50 million respectively, from application onward, according to Duane Morris. Families setting up outside their home country should take local legal advice before choosing a domicile.
“Masttro is a family office engine that can consolidate all types of information related to the family. Not only the financial, the lifestyle assets, also legacy and different activities that are related to the family.”

The Ultimate Guide to Family Office Software in 2026

Is your family ready for a single-family office?
If the thresholds above put you near the line, these six questions usually settle it.
If you answered yes to fewer than four, an MFO or an outsourced model will likely serve the family better for now. Our step-by-step guide on how to start a family office covers the next decisions if you are ready.
How does technology change the minimum?
Software lowers the practical minimum because it replaces work that would otherwise need more staff. A lean office of three people can run institutional-quality consolidated reporting if data arrives automatically instead of being downloaded and rekeyed.
Masttro's family office software connects to 750+ custodians and banks in 40+ countries, consolidates every asset class and entity into one live view with real-time data access, and uses Documents AI to read capital call notices, NAV statements and K-1s. Stonebridge Family Office cut its monthly reporting from 8–10 hours to a few hours after moving to Masttro, and Jefferson River Capital runs a $1B+ portfolio with 200+ alternative investments on a small team. Masttro's pricing is flat and not tied to assets under management, so the cost does not grow as the family's wealth does.
For a side-by-side view of the platforms families use, see our list of the best family office software, or download The Ultimate Guide to Family Office Software for features, pricing models and best fit.
Which family office model fits your net worth?
- $100M+ in investable assets: an SFO is viable, and becomes comfortable from about $250M.
- $25M–$100M: an MFO offers shared professional investment management at a fraction of the cost.
- $10M–$30M: an outsourced or virtual family office coordinates private banks and advisors.
- Any level: complexity (entities, countries, private markets, generations) can move the threshold up or down.
Frequently asked questions
How much money do you need to start a family office?
Most advisors recommend at least $100 million in investable assets for a single-family office, with $250 million or more as the comfortable range. Offices managing $250 million or less still spend about $0.9 million a year to operate, per J.P. Morgan's 2026 report.
Is $10 million enough for a family office?
Not for an SFO. At $10 million, the running costs would consume most of the portfolio's returns. Families at this level typically use an outsourced family office or a virtual family office built around a private bank or independent advisor.
Is $50 million enough for a single-family office?
It is possible but expensive. A typical small office costing about $0.9 million a year would consume close to 2% of $50 million annually. Most families at this level get better value from an MFO.
How much does a family office cost per year?
J.P. Morgan's 2026 survey found average annual costs of $0.9 million for offices managing $250 million or less, $1.7 million for $250 million–$500 million, $3.3 million for $501 million–$999 million, and $6.6 million for $1 billion and above.
What is the difference between a single-family office and a multi-family office?
An SFO serves one family and is owned and controlled by it. An MFO serves several families with a shared team and is usually a registered investment adviser. MFOs cost less per family but give each family less control over investment strategies and staffing.
What is the minimum for a family office in Singapore?
Under the Section 13O and 13U tax incentive schemes, family office funds must hold at least S$20 million and S$50 million respectively, from the time of application.
“We use the CPA in every investment committee, especially the portfolio breakdown capabilities.”
“I appreciate the ease of use and the pre-produced library of reports that Masttro provides. It has significantly streamlined our processes, allowing us to produce reports in minutes that would have taken hours before.”
"I really appreciate their amazing customer support. The team is attentive and dedicated, and they don't just stop at software implementation. They've been really helpful with different scenarios."