
Risk, return and the efficient frontier
Where the portfolio sits on the efficient frontier, and a better mix at the same risk.
Using our current holdings, calculate our expected annualized return, volatility, Sharpe ratio and correlation across asset classes. Then build an efficient frontier and show whether a different allocation could raise expected return without adding risk. Keep illiquid assets fixed, show the proposed allocation and quantify the improvement.
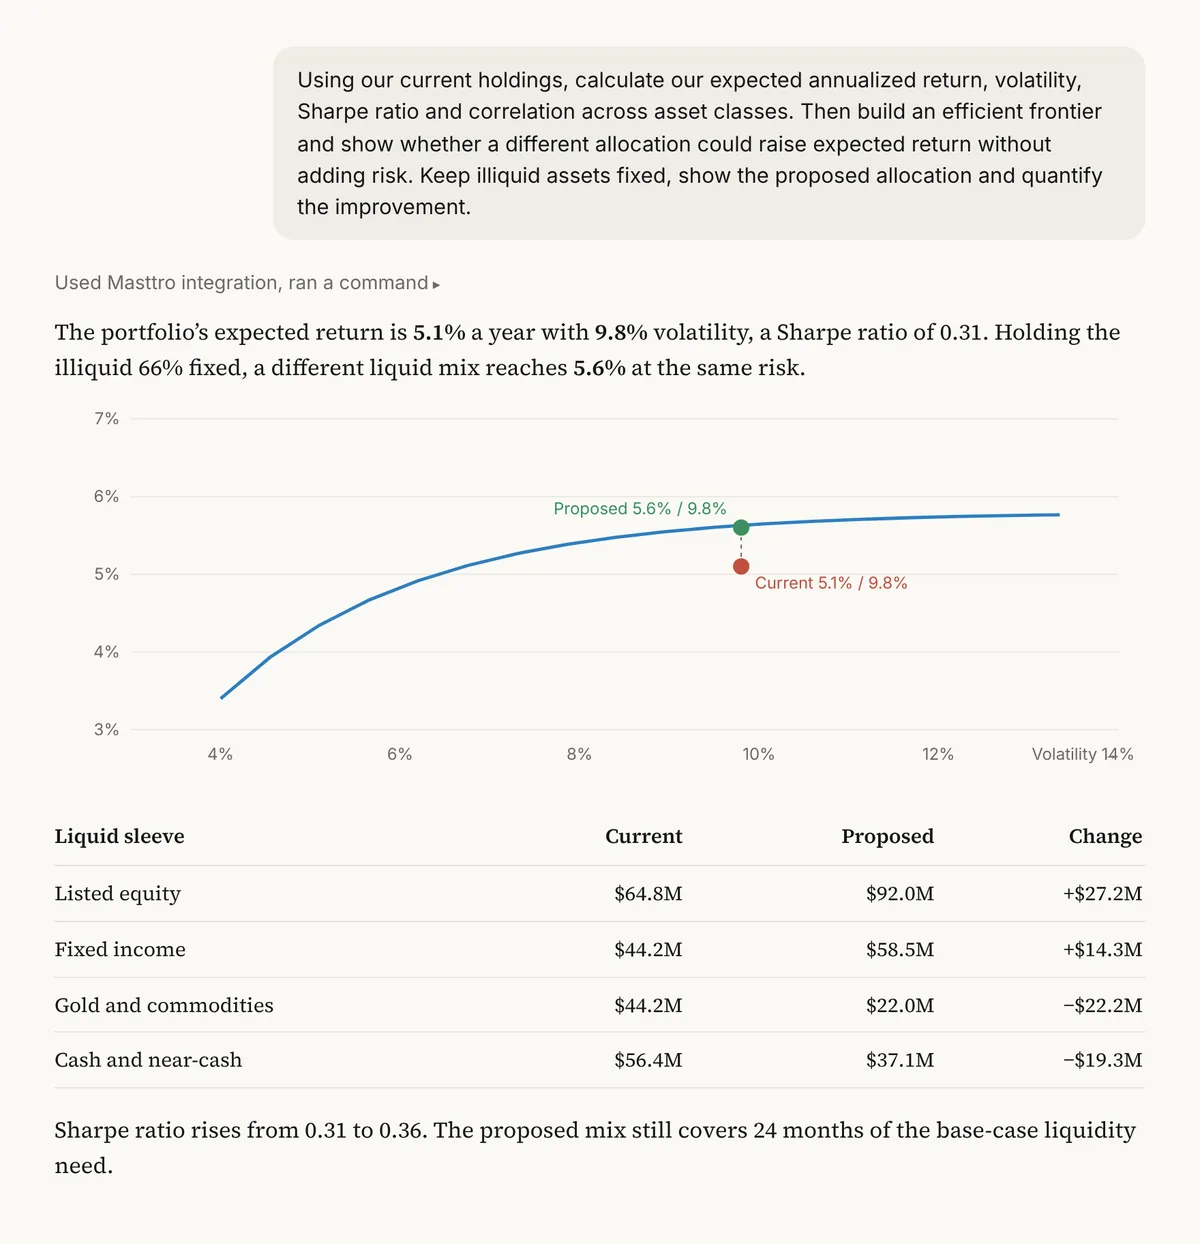
Illustrative output based on Masttro's demo family office data.
Expected return, volatility, Sharpe ratio and correlations.
Where the portfolio sits against the best available mixes.
A proposed mix at the same risk, with illiquid assets held fixed.
Run as written. Use the follow-ups to loosen constraints on real estate.
Why plot the portfolio on an efficient frontier?
Most family portfolios grew by accretion: a mandate here, a property there. The result is rarely the most efficient mix for the risk the family is taking.
This prompt measures the current portfolio and shows whether a different allocation could raise expected return without more risk. It keeps illiquid assets fixed, because they can't be rebalanced on paper.
Shows how much a better mix could add.
Illiquid holdings stay where they are.
Capital market assumptions come from the AI and are shown.
Questions about this prompt
Where do the assumptions come from?
Holdings and historical returns come from Masttro. Forward-looking capital market assumptions come from the AI tool.
Why keep illiquid assets fixed?
Private funds and property can't be resized quickly, so the proposal only moves assets that can actually be traded.
Can I see the correlations?
Yes. The first follow-up shows the correlation matrix.
Is this investment advice?
No. It is an analysis to discuss with your CIO or advisers.


