
Risk radar with stress-test sliders
Sliders that stress the portfolio live, with presets for historical scenarios.
Build an interactive risk radar with stress-test sliders for [equity markets, interest rates, oil, the US dollar and London property]. As I drag a slider, recalculate net worth, liquidity, cash runway and each entity’s value. Add preset buttons for [1970s stagflation], [2008], [a dollar crash] and [2022].
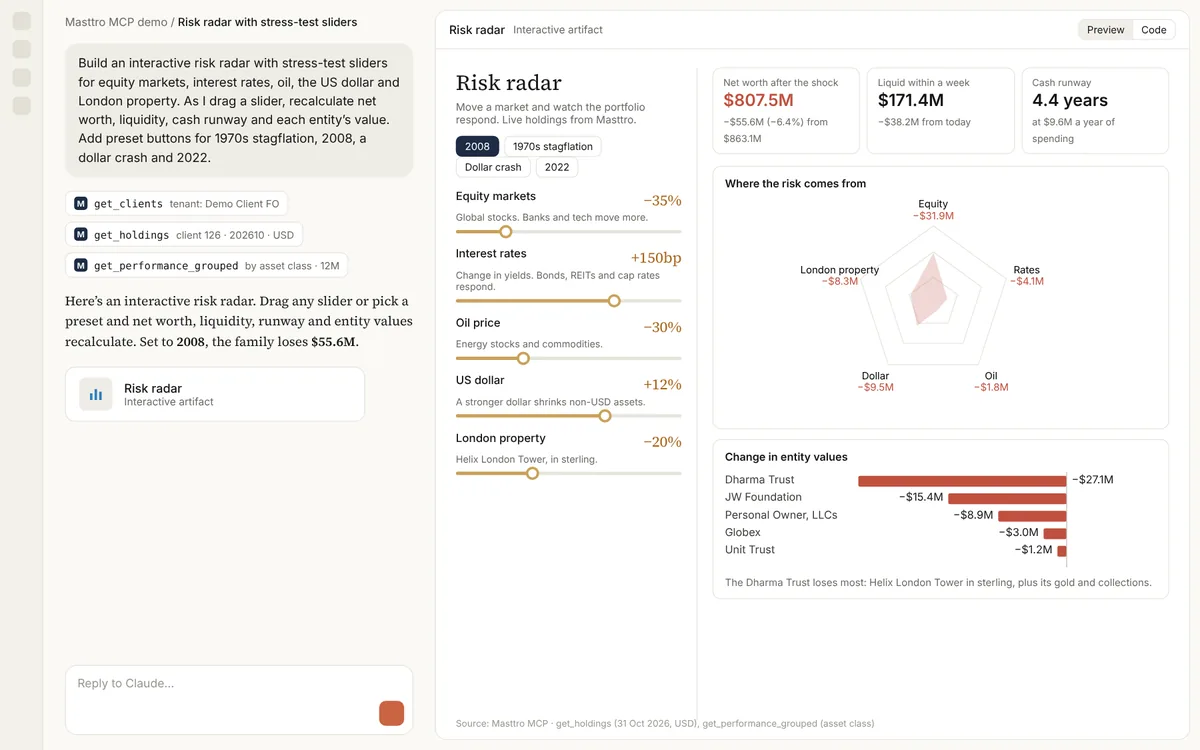
Illustrative output based on Masttro's demo family office data.
Stress equity markets, rates, oil, the dollar and property.
Net worth, liquidity, cash runway and entity values update as you move.
One-click stagflation, 2008, a dollar crash and 2022.
Replace the bracketed risk factors and presets with the ones your family worries about.
Why build an interactive risk radar?
Static stress tests answer the question that was asked. A principal in a meeting usually wants to ask the next one, and the one after that.
This prompt has the AI build sliders over your holdings by asset class, currency, geography and entity, so any combination of shocks can be tested live.
Test any combination of shocks.
See which part of the structure is exposed.
A follow-up stores your settings as a custom scenario.
Questions about this prompt
What data drives the radar?
Holdings by asset class, currency, geography and entity in Masttro.
How are the shocks applied?
The AI applies each slider's move to the relevant holdings and recalculates. Its assumptions should be stated in the dashboard.
Can I add other risk factors?
Yes. A follow-up adds a slider for private equity marks, and you can edit the bracketed list.
Which AI tools can build it?
Claude can build interactive dashboards in the conversation. Results vary by tool.


