
Historical stress test
Four scenarios side by side, with the losses, the drivers and the cash left.
Stress-test our portfolio against [a 1970s-style stagflation], [a 2008-style financial crisis], [a 2022-style stock and bond sell-off] and [a 30% fall in equities with a 15% fall in real estate]. Estimate the hit to net worth, name the holdings that drive the losses, and tell me how much liquid capital we’d have left.
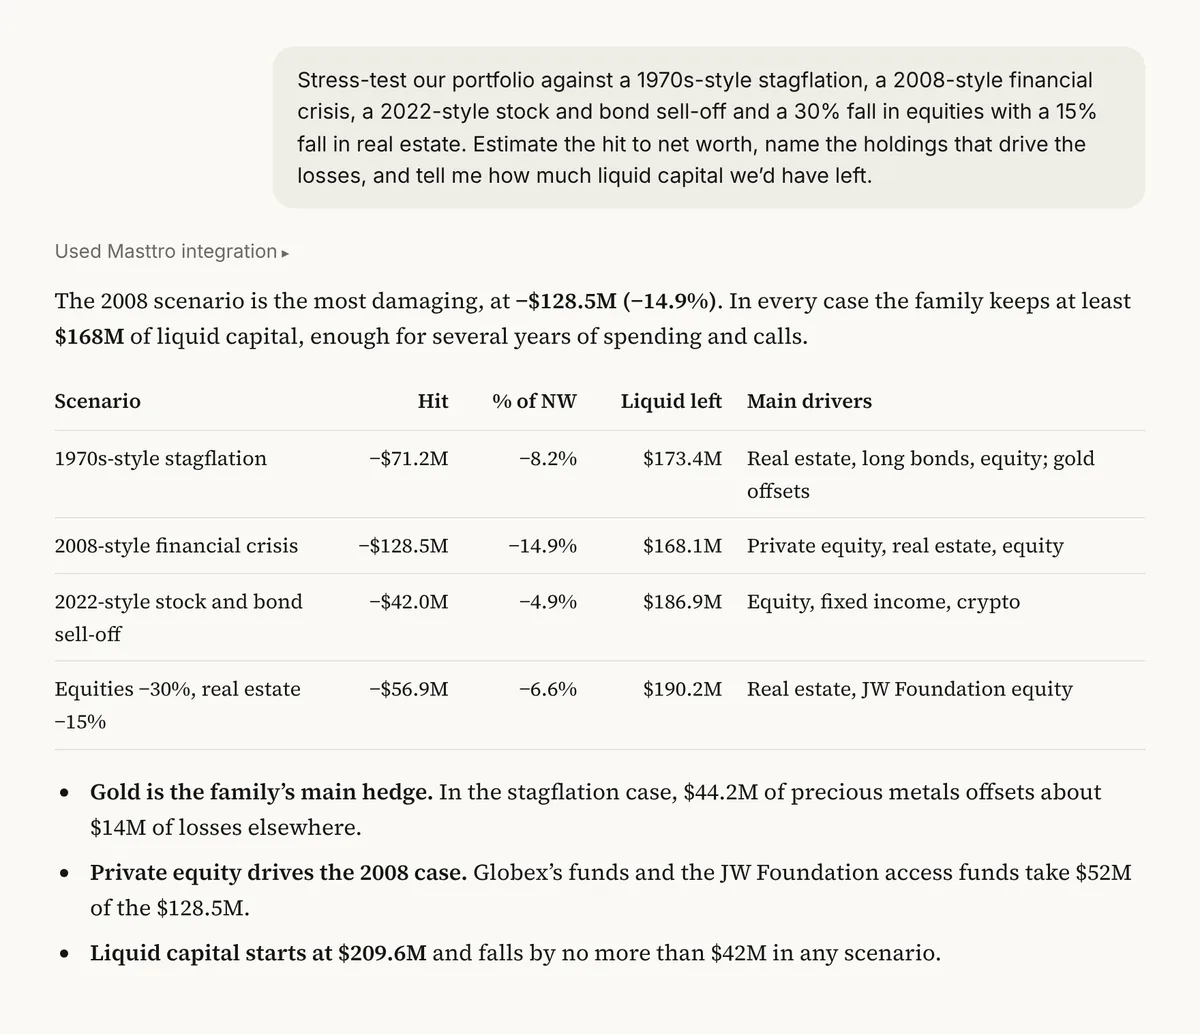
Illustrative output based on Masttro's demo family office data.
Stagflation, 2008, the 2022 sell-off and a combined equity and property fall.
The holdings responsible for most of each loss.
Liquid capital remaining after each scenario.
Keep or replace the four bracketed scenarios with the ones your family cares about.
Why test against historical scenarios?
Historical crises give a concrete shape to risk. 'What if 2008 happened again?' is a question a principal understands immediately, and different crises hit different assets.
This prompt applies four scenarios to your holdings by asset class, sector and geography, then reports the loss, the drivers and the liquidity left. It turns an abstract risk discussion into numbers.
Scenarios the family recognizes.
Inflation, credit and rate shocks compared.
Shows whether the family could ride it out.
Questions about this prompt
How are the scenario losses estimated?
The AI applies typical moves from each historical period to your holdings by asset class, sector and geography, and should state the moves it used.
Can I add my own scenario?
Yes. Edit the bracketed scenarios or use the follow-up that adds a dollar crash.
Can I see the result by entity?
Yes. The first follow-up shows which entity loses most in the 2008 case.
Can I make it interactive?
Yes. The last follow-up turns it into a risk radar with sliders.


